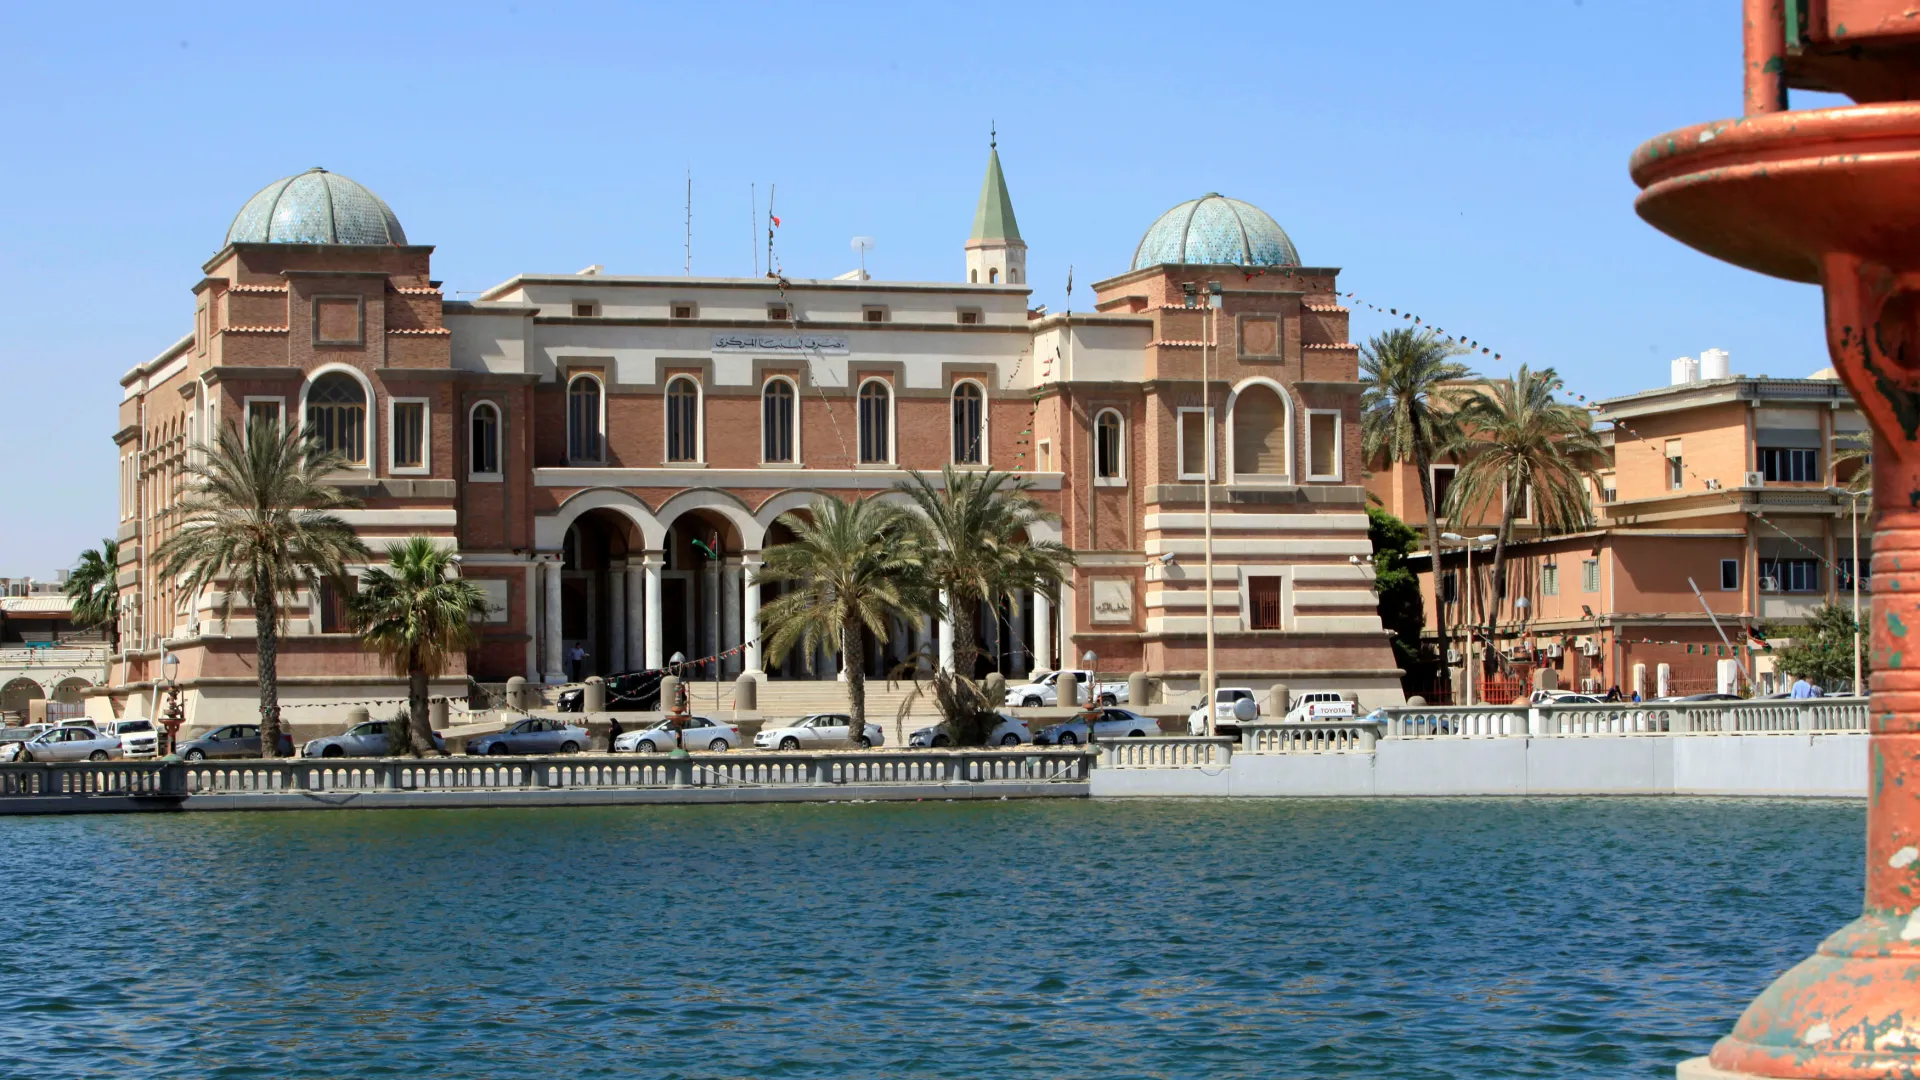
Tag: central bank

Exclusive.. Al-Sanussi: “Central Bank Approves Letters of Credit Today for Companies Affiliated with the Oheiba Family… Raising Questions Over Why They Were Favored Over Other Traders”

Media personality Ahmed Al-Sanussi said: The Central Bank of Libya approved letters of credit today for companies belonging to only one family, the Whiba family, according to our sources.

He questioned the reasons behind these approvals and why these companies were favored over other traders.

Exclusive.. Central Bank of Libya to Sada: Our Foreign Reserves Exceed LYD 400 Billion and Cover the LYD 210 Billion Money Supply

The Central Bank of Libya confirmed to our source that the country’s foreign-currency reserves are in a comfortable position and cover the money supply of the Libyan dinar, known as the money supply, which stands at LYD 210 billion. Meanwhile, liquid and readily convertible foreign reserves exceed LYD 400 billion, indicating that monetary balance is in place.

The Central Bank can also achieve stability if public spending is controlled, deficit financing is avoided, and a rapid economic reform program is put in place.

Exclusive.. “Central Bank”: $380 Million Sold Today for Letters of Credit and Personal Purposes

The Central Bank of Libya confirmed to our source that it continues to sell foreign currency today, with $300 million sold for letters of credit and $80 million for personal purposes.

The Central Bank explained that foreign-currency sales operations are continuing in an organized manner until all letters of credit and personal-purpose requests are fully settled, noting that the pace of sales will accelerate in the coming period amid the relative increase in oil revenues.

Al-Shalawi: “Between Oil Figures and Central Bank Figures… Where Does the Picture of Libya’s Public Finances Become Complete?”

Written by oil and economic expert Abdelmonsef Al-Shalawi

A reading of the January–August 2026 data: Transparency matters, but the financial picture remains incomplete without the missing link

When official figures are published, their real value does not lie solely in the size of the figure itself, but in our ability to understand what lies behind it: Where did it come from? When was it realized? Where was it deposited? How was it transferred? What was spent from it? And on which items?

From this perspective, the data published by public institutions are not merely financial tables, but pieces of a single economic picture that should ultimately come together before citizens, decision-makers, and experts.

In this context, the Central Bank of Libya’s statement on revenues and expenditures through August 31, 2026, comes alongside the monthly data that the National Oil Corporation continues to publish on production, revenues, and transfers.

A professional reading of these data should not begin with the question, “Which figure is correct?” but rather with the more important question:

How can we connect the figures issued by different institutions within a single financial system that makes the movement of public funds traceable from source to destination?

The National Oil Corporation… Disclosure of the Productive Sector

It is fair to say that the National Oil Corporation has made significant progress recently in publishing data related to production and revenues.

The Corporation regularly publishes summaries covering crude oil production, the state’s share, partners’ share, quantities available for export, refining quantities, oil and gas uses, as well as revenues collected, transfers, and the budget received.

In its August 2026 data, for example, the Corporation announced production of more than 43.3 million barrels of crude oil. It also announced the transfer of approximately $2.555 billion to the sovereign account, in addition to royalties and concession contract taxes, while explaining the mechanism for handling fuel supply credits.

This disclosure practice deserves recognition because it provides economic and oil-sector observers with important primary material for understanding the sector’s performance.

The publication of data is also not limited to revenues, but extends to natural gas and the quantities delivered to various sectors, which is important when assessing the Libyan energy economy as a whole.

But the Oil Figure Is Not the Final Financial Figure

This is where I believe a point worthy of further calm discussion begins.

The revenue announced by the National Oil Corporation and the revenue appearing in the Central Bank of Libya’s data are not necessarily the same figure at the same time or according to the same accounting basis.

The Corporation deals with production, sales, collection, transfers, and reconciliations, while the Central Bank of Libya presents revenues and expenditures from the perspective of flows entering public accounts and what is recorded and spent within the financial system.

Therefore, comparing two figures from different sources without knowing the accounting date of each figure, the nature of the revenue, the collection mechanism, the reconciliation process, and the entity through which the financial flow passed may lead to hasty conclusions.

The Corporation had previously explained, in one of its statements, that revenues collected in February represented crude oil sales for the month of January. It also explained the mechanism for reserving funds to cover part of the cost of fuel.

These details are not marginal; they are at the heart of understanding the differences between the figures.

What Does the Central Bank of Libya’s Statement Say?

The Central Bank of Libya’s statement through August 31 provides an important picture of the revenue and expenditure side.

Total revenues amounted to approximately LYD 98.98 billion, including around LYD 80.8 billion in oil sales revenues and LYD 15.3 billion in oil royalties, while other revenues from taxes, customs, telecommunications, and other sources were significantly lower.

Recorded expenditure amounted to approximately LYD 68.61 billion, distributed mainly among salaries, operational expenditures, subsidies, and development. The statement itself indicates that the figure for the first expenditure category does not include August salaries, an important detail when reading total expenditure and avoiding treating it as a final, closed figure for the year.

These figures alone reveal a fundamental economic reality:

Libya’s public finances remain highly dependent on oil revenues, while the largest share of public expenditure continues to go toward current, social, and operational items rather than investment and development.

This is not an observation about any particular institution, but rather an issue concerning the structure of the economy and public finances as a whole.

The Corporation Is Not the Entire Public Finance System

From here, I believe it is important to distinguish between institutions and their respective roles.

The National Oil Corporation is the technical and commercial arm of the oil sector. It is responsible for production, development, exports, and managing oil activities within its mandate.

The management of public finances, setting priorities, the budget, public expenditure, reconciliations, and government accounts, on the other hand, constitute a broader system than the Corporation itself.

Therefore, holding a single institution responsible for explaining the entire movement of public funds may not be institutionally accurate.

At the same time, calls for greater disclosure by the Corporation remain legitimate, as do calls for more detail from the Central Bank of Libya. But the greater need is for these disclosures to come together within a single system.

The Missing Link We Need: The Ministry of Finance

This brings me to the most important point in this analysis.

For citizens and experts to understand what happened to public funds during the first eight months of 2026, we need an integrated view from the Ministry of Finance that connects revenues appearing in government accounts with actual expenditure, clarifies the basis of recording and reconciliation and the timing of revenue recognition, and links appropriations to actual expenditures.

The Central Bank of Libya’s statement provides an important part of the picture.

The National Oil Corporation’s reports provide another important part.

But without detailed and systematic financial data from the Ministry of Finance, a gap remains between the oil figure and the final financial figure.

This gap is not necessarily evidence of a problem or violation; rather, it is an information gap that should be closed if we want to achieve the highest levels of financial transparency.

True transparency does not mean that every institution simply publishes its figures.

More mature transparency means that a researcher can take a figure from one institution, trace it through the next institution, and determine where it ended up, how it was reconciled, and under which item it appeared in government accounts.

What We Need Is Not More Figures… But More Connections

Perhaps the most useful step now is to move from the concept of “individual disclosure” to the concept of “integrated disclosure.”

In other words, we need a unified table or periodic statement through which an observer can follow the following path:

Oil production

Sales and exports

Revenues collected

Reconciliations and deductions

Transfer to sovereign accounts

Revenue recorded in public finances

Appropriations

Actual expenditure

Cumulative balance or deficit

Only then can we move from simply reading figures to reading the economy itself.

What Do the Eight-Month Figures Tell Us?

First, they tell us that the oil sector remains the backbone of public revenues.

Second, they tell us that the volume of current and social expenditure remains large compared with development expenditure. The Central Bank’s statement shows that expenditure under the third category, namely development, amounted to only around LYD 912.8 million, compared with LYD 46.9 billion for the first category and LYD 11.8 billion for subsidies.

These ratios deserve an independent economic discussion because they concern not only the size of expenditure, but also the nature of expenditure and its ability to create added value, employment opportunities, and diversify sources of income.

The economy’s dependence on oil also means that any improvement in production or prices has a direct impact on public finances. Conversely, any decline in production, prices, or exports quickly creates pressure on the budget, exchange rate, and public expenditure.

Fairness to the Corporation Does Not Mean Exempting It from Accountability

It is important here to emphasize a point that I consider essential in any professional discussion.

Presenting the National Oil Corporation in a positive light does not mean exempting it from criticism or oversight.

On the contrary, the best protection for the National Oil Corporation is greater professional transparency.

The more detailed, consistent, and comparable the data become, the easier it is to defend the Corporation when the figures are in its favor, and the easier it is to identify any shortcomings when problems do exist.

This is the difference between institutional defense and personal defense.

We do not need to defend individuals.

We need to defend the institution, the sector, public funds, and the rules of governance.

Conclusion

The data published by the National Oil Corporation and the Central Bank of Libya for the period from January to August 2026 provide highly important material for understanding the Libyan economy. At the same time, however, they reveal the need for a higher level of integration in financial disclosure.

The National Oil Corporation publishes an important part of the oil story.

The Central Bank of Libya publishes an important part of the revenue and expenditure story.

But the complete story requires the financial link that connects the two systematically. This highlights the importance of the regular publication of detailed financial data by the Ministry of Finance.

Therefore, the question I consider more important than “Where did the money go?” is:

How did the money move in the first place, from the moment the barrel was produced to the moment the revenue was recorded and spent?

When we can answer this question using interconnected figures, clear dates, and disclosed reconciliations, we will have moved from formal transparency to auditable transparency.

And this is the level Libya needs today.

Not more arguments over the figures…

But more connections between the figures.

Figures separated from their context may confuse public opinion. But when they are connected to one another, they become a tool for understanding the economy, evaluating performance, and protecting public funds.

Exclusive.. In Violation of Central Bank Instructions.. 300 Million Financing for Building Materials Company Raises Questions Over Benghazi Branch Exceptions

In violation of the instructions of the Central Bank of Libya, the Central Bank’s Benghazi branch granted financing worth 300 million to Al-Bareeq Al-Awal Building Materials Company, headed by “Faisal Naji Ahmed Wahiba” and his partner, “Ibrahim Misbah Ahmed Wahiba.”

The company was exempted from the suspension of financing, which, according to our sources, contributed to the rise in the dollar exchange rate on the parallel market.

Exclusive.. Benghazi Central Bank Grants Exceptions for Bank Financing Despite Suspension.. Sources Link Them to the Rise in the Parallel Exchange Rate

Our source exclusively obtained correspondence from the Central Bank of Libya’s Benghazi branch regarding a request by the National Commercial Bank to grant an exception to Safo Food Industries Company to obtain financing for the establishment of a beverage production plant, in view of the project’s economic importance and its contribution to the national economy, according to correspondence from the Banking and Monetary Control Department dated July 20, 2026.

The bank explained that the approval was based on Circulars No. (12/2025) and (25/2025) issued by the Banking and Monetary Control Department, allowing an exception to the maximum expansion limit of the credit portfolio, which may not exceed 7%, while temporarily suspending the granting of direct and indirect financing to legal entities.

It stressed the need to comply with all regulations and circulars issued by the Banking and Monetary Control Department, provide adequate guarantees, and exercise due diligence in this regard.

Exclusive.. Central Bank: Banning Imports Through the Black Market Will Enable Authorities to Set Commodity Prices and End Traders’ Excuse of the Dollar Rate

The Central Bank of Libya exclusively confirmed to our source that following the issuance of the two decisions by the Ministers of Economy banning the import of goods through the black market, the Ministry of Economy and the Central Bank will be able to impose specific prices on commodities based on the letters of credit.

It added: “Traders will no longer have an excuse to link prices to the dollar rate on the market.”

Al-Shahoumi Writes: Central Bank of Libya and Ministry of Economy, Coordination or an Impending Confrontation?

The founder of the Libyan Stock Market and finance professor, Suleiman Al-Shahoumi, published a post in which he wrote: Central Bank of Libya and Ministry of Economy, coordination or an impending confrontation?

Is the Central Bank, through coordination with the Ministry of Economy, trying to curb inflation or to rein in the exchange-rate turmoil?

By the end of this month, Ministry of Economy and Trade Decision No. (449) of 2026 will come into effect. The decision prohibits commercial goods from entering Libya outside the banking channels and prohibits customs clearance of any shipment before its banking and customs procedures have been completed and proof of its actual value has been provided. The decision makes an exception for individual business owners within an annual ceiling and sets out arrangements for shipments whose procedures had begun before this date.

The idea itself is sound. Bringing trade into the banking system makes the movement of money visible, helps combat money laundering, and allows the Central Bank to determine the actual level of demand for dollars. There is no disagreement over the objective. The disagreement concerns the sequencing and whether the official channel is ready to receive what will be directed through it in just a few weeks.

Let us begin with what matters to the citizen. When the price of a commodity rises at a store, we always assume that the reason is the rise in the dollar. This is only partly true. The commodity reaches the consumer after passing through a long chain that begins with financing and opening a letter of credit, followed by purchasing, shipping and insurance, then the port, customs, clearance, storage and transportation, and finally wholesale and retail. Any delay at any link in this chain becomes a cost, and every cost ultimately reaches the consumer. The citizen does not pay only for the commodity itself; they also pay for the journey it took to reach them.

What the figures say:

The figures announced for the first half of this year reveal a different picture from what is commonly believed. Letters of credit amounted to $8.3 billion, representing more than half of foreign-currency usage. This means that trade is already largely within the banking system and that imports are not all taking place outside it, as is often claimed. As for the portion targeted by the new decision, no figure has been announced for its size, making it difficult to prepare to accommodate something whose volume we do not know.

The same figures contain another indication worth considering. Foreign-currency cash sales for personal purposes fell by more than half, while transfers rose to $2.2 billion, compared with less than $300 million last year. Demand for dollars has therefore not declined; it has simply moved from one channel to another. This is precisely what should be expected once the Ministry of Economy’s decision takes effect: some trade will enter the letters-of-credit system, some will temporarily stop, and some will seek another, more expensive route. The additional cost will not be borne by the trader out of pocket; it will be added to the price.

There is a third figure that sums up the entire problem. Traders’ cards, which are supposed to serve small importers, did not exceed $38.9 million, or just two dollars out of every thousand. The tool intended for small traders is virtually inactive at the very moment small traders are being asked to move into the banking system. The exception included in the decision gives them the right to import, but it does not provide them with dollars or with the banking instrument through which the import process can be carried out.

The root of the gap is not imports:

The official exchange rate today is around LYD 6.34 per dollar, while the parallel market is at approximately LYD 9.25. Before discussing the gap, it is only fair to say that the proper comparison is not with the announced rate, but with the rate actually paid by the importer after adding the fee imposed on foreign-currency sales. The real gap is narrower than commonly stated, but it remains significant, and the fee itself becomes part of the cost of the commodity and ultimately reaches the consumer.

The reason behind this gap is not fundamentally commercial. The Central Bank itself attributed the two devaluations of the dinar within less than a year to government spending by two governments, the absence of a unified budget, and declining oil revenues. In other words, the imbalance originated on the spending side, not the import side. Restricting trade may reduce recorded demand for dollars, but it does not address the cause that created the gap. Anyone who addresses supply without addressing the underlying cause will find themselves facing the same problem months later, only in a new form.

A ban with a date and a facilitation promise without one:

The Central Bank and the Ministry of Economy say they are coordinating, and this is true on the surface. The Central Bank was the one that requested this decision and announced that it would accelerate foreign-currency requests in response to the Ministry of Economy’s decision.

But there is a fundamental difference between the two commitments. The ban was issued as a binding decision, with a specific date and a clear penalty: suspension of customs clearance. The facilitation, however, came in the form of a general agreement and a promise without a date, without a figure, and without a maximum timeframe for completing a letter-of-credit request. When the ban is clearly defined while the facilitation is not, it is natural for the first to be implemented on schedule while the second is delayed. This is precisely where regulation can turn into a new bottleneck.

The question of banks’ readiness also remains. The technical payment infrastructure is functioning and expanding, and this is not in doubt. However, foreign trade transactions are concentrated in a small number of banks, with one bank accounting for approximately $2.6 billion of usage in half a year. Adding thousands of small traders to the same banks means longer queues, not broader service. Moreover, the only practically available instrument is the letter of credit, which is designed for large transactions and requires guarantees that small traders do not possess. There is no short-term financing to cover the period between payment, arrival and sale, nor is there a credit record that allows a trader to be assessed based on their performance rather than their collateral. In addition, part of the time required to process a letter of credit is spent outside Libya, at correspondent banks and in meeting compliance requirements — time that cannot be controlled.

What should be done:

The solution is not to cancel the decision, but to support it with measures that make it implementable without making citizens pay the price. First, there should be a publicly disclosed estimate of the volume of imports currently conducted outside the banking system, because preparedness requires a figure, not an impression. Second, registration should be opened to importers before implementation, with the number of applications processed and the time taken measured, and the effective date should be linked to the results of this test rather than to a calendar date. Third, a genuine instrument for small traders should be activated, with a realistic ceiling and a banking product that actually works; otherwise, the exception will remain merely a provision on paper. Fourth, a maximum timeframe should be announced for processing letters of credit and transfer requests, with the actual average processing time published monthly. A trader can tolerate a slow procedure if its duration is known, but cannot tolerate an unknown procedure because uncertainty itself is added to the price. Fifth, there must be a clear arrangement for shipments that have already been contracted and actually shipped, because port delay penalties and storage costs will ultimately be passed on through the price of the commodity.

In the longer term, the Central Bank should address the source of the gap rather than its symptoms. It should announce a regular, quantified program for dollar sales for letters of credit and transfers, expand the number of banks capable of handling foreign-trade transactions, and publish monthly data on applications submitted, executed and rejected. The Ministry of Economy should consolidate procedures into a single window with announced timelines, measure and publish the time and cost of customs clearance at ports, and shift from monitoring the final price to identifying where costs have increased along the supply chain. It should ask one question about every new regulation: How many traders will this drive out of the market? Because the number of importers is not merely a matter of prices; it is a matter of supply security. If the market becomes dependent on a small number of companies, the failure of one of them can affect the entire market within days.

How should the policy be assessed after implementation?

Two months from now, it may be said that the rate of compliance with the decision is high, and this will be presented as a success. But that is not the measure of success. There are three criteria: Has the gap between the effective official exchange rate and the parallel-market rate narrowed? Has the time between submitting a letter-of-credit application and the shipment leaving the port decreased? And has the dinar price of the basic-goods basket stabilized compared with its price in the country of origin?

If all three improve together, the friction contributing to higher inflation will genuinely have declined. If only one improves, it means the bottleneck has not been resolved; it has simply moved from the foreign-exchange market to store shelves.

Ultimately, the goal is not to prevent traders from using another route, but to make the official route faster, cheaper and broader so that no one needs an alternative. The real test of this decision will not be the number of shipments it stops, but the price of the commodity three months after its implementation.

Exclusive.. Central Bank: We Will Accelerate Foreign Currency Sales to Banks Following Import Regulation Decisions

The Central Bank of Libya exclusively confirmed to our source that it will accelerate approvals for letters of credit and foreign currency sales to banks in order to ease financial demand, particularly following the issuance of decisions by the two economy ministers prohibiting imports except through banking transactions.

It added: “This week has seen a faster pace, reaching $600 million, and we will continue working toward the targeted amount of $2 billion for letters of credit and transfers.”

Al-Gmati: “Has Financial Inclusion Succeeded in Libya? A Critical Review of the Central Bank of Libya’s Experience”

Written by: Helmi Al-Gmati, Professor of Economics at the University of Benghazi

The Central Bank of Libya has succeeded in making significant progress in digitalization and electronic payments, but it has not yet achieved full financial inclusion in its true economic sense.

In other words, we have succeeded in shifting a large portion of transactions to mobile phones and cards, but we have not yet succeeded to the same extent in transforming the banking system into a comprehensive tool for production, savings, credit, and investment.

First: Where Has the Central Bank of Libya Succeeded?

The major leap in electronic payment infrastructure cannot be denied. According to Central Bank data from the beginning of 2026, the number of points of sale exceeded 170,000, the number of activated cards exceeded 5.5 million, and the number of subscribers to banking applications exceeded 4.29 million. Mobile banking applications recorded tens of millions of transactions involving substantial financial values.

Instant transfer services such as LYPay and OnePay have also expanded. A National Financial Inclusion Strategy for 2025–2029 was launched, with projects covering financial accounts for underserved groups, digital identity, and digital financial services. In June 2026, expansion continued with the introduction of global Visa card acceptance through local points of sale and SoftPOS technology.

So, from the perspective of technology and digital payments, there has clearly been significant success.

But Where Is the Problem?

Financial inclusion is not simply a banking application

There is considerable confusion in official discourse between Financial Inclusion and Digital Payments.

Digital payments are part of financial inclusion, but they are not financial inclusion in its entirety.

True financial inclusion means that citizens and businesses are able to:

  • Open an account easily.
  • Save securely.
  • Obtain financing and credit.
  • Insure against risks.
  • Access financial services at an affordable cost.
  • Finance their businesses and invest and produce.
  • Obtain fair banking services across all regions and population groups.

And this is where the Libyan problem becomes apparent.

Second: The Citizen Has Entered the App, But Has He Entered the Real Financial Economy?

This is the fundamental point.

A citizen may have a bank card, a mobile application, money-transfer services, and the ability to make electronic payments.

But can they obtain a loan to establish a factory?

Can a young person obtain financing for a small business?

Can a woman establish an economic activity and obtain suitable financing services?

Can a farmer obtain seasonal financing?

Can small and medium-sized enterprises easily access credit?

Frankly, the gap remains significant.

Therefore, it can be said that Libya has achieved an expansion in digital inclusion, but it has not yet achieved productive financial inclusion in its full sense.

Third: The Major Libyan Paradox

Libyan banks hold substantial liquidity, while the economy suffers from weak financing.

This is a serious economic paradox.

There is a great deal of money within the banking system, but limited financing for production.

In other words, citizens can transfer money electronically more quickly, but they cannot with the same ease obtain financing to establish a business that produces that money.

Here, digital transformation becomes merely an improvement in the means of circulating money, rather than necessarily an improvement in the process of creating wealth and production.

Fourth: Has the Central Bank Succeeded in Reducing Dependence on Cash?

I would say that the success has been partial and significant, but not complete.

The expansion of points of sale, banking applications, and instant transfers has indeed contributed to reducing the need for cash in some transactions. The Central Bank of Libya has also, over the years, built an electronic payments and settlement infrastructure to support multi-channel banking services.

However, the continued problems of trust in banks, access to liquidity, the informal economy, the parallel foreign-exchange market, and the weak availability of advanced services outside the main urban centers mean that cash still plays a greater role than it should in the Libyan economy.

The Central Bank of Libya has succeeded in building the road toward financial inclusion, but it has not yet reached its destination.

Yes, it has succeeded in digitalizing transactions, but it has not yet succeeded to a sufficient degree in digitalizing the productive economy, financing citizens and small businesses, and transforming savings into investments.

Therefore, my economic assessment is that what has been achieved in Libya so far represents major success in the transition toward digital payments and partial success in financial inclusion, but it does not yet constitute genuine and comprehensive financial inclusion.

True financial inclusion is not measured solely by the number of cards and points of sale, but by the number of citizens and businesses that have moved from outside the formal economy into it, from consumption to production, and from a need for financing to the ability to invest.

In my view, there is still much more work ahead for the Central Bank of Libya and commercial banks.

Central Bank of Libya

Central Bank to Sada: “$2 Billion to Be Injected to Settle Existing Letters of Credit, with Accelerated Approvals and Foreign Currency Sales to Banks”

The Central Bank of Libya told our source exclusively that next week it will inject $2 billion to settle existing letters of credit. The week will also see an acceleration in the approval of letters of credit and the sale of foreign currency to banks in large amounts for various purposes.

The Central Bank added that the letters of credit will be processed following a thorough review conducted in coordination with the Ministry of Economy.

Meanwhile, banks will continue selling U.S. dollars in cash at all branches.

Central Bank of Libya

Exclusive.. Libya Central Bank Expects Faster Approvals for Letters of Credit and Dollar Sales to Banks Next Week

The Central Bank of Libya told our source exclusively that next week will see an acceleration in the granting of approvals for letters of credit and the sale of foreign currency to banks in large amounts for letter-of-credit purposes, following a review conducted in coordination with the Ministry of Economy.

The Central Bank added that banks will continue selling U.S. dollars in cash at all branches.

Central Bank to Sada: Foreign Currency Reservation Platform Opens Today; Individual Foreign Currency Sales to Begin on Sunday

The Central Bank of Libya announced in an exclusive statement to our source that the foreign currency reservation platform would reopen for new applications starting at noon today.

The Bank stated that it has begun accepting new reservation requests from individuals through the system.

It also confirmed that sales of U.S. dollars for personal purposes—both in cash and through bank cards—will commence next Sunday.

The announcement comes as part of the Bank’s efforts to resume and facilitate access to foreign currency services for individuals following the recent technical disruptions.

Exclusive: Al-Gmati: The Central Bank of Libya Incident Is a Wake-Up Call to Strengthen Cybersecurity and Protect Financial Stability

Helmi Al-Gmati, Head of the Economics Department at the University of Benghazi, told our source exclusively that the Central Bank of Libya is not merely a banking institution but one of the most important pillars of the country’s economic security, given its role in managing monetary policy, foreign reserves, payment systems, and sensitive financial data.

Al-Gmati explained that the official information released so far indicates that a cyber incident targeted certain technical systems at the Bank. Immediate measures were taken to contain the incident and isolate the affected systems. He stressed that core operations have continued uninterrupted and that there is currently no evidence of any direct impact on customers’ accounts or balances, while technical investigations remain ongoing to determine the exact scope and causes of the incident.

He added that the issue extends beyond the technical dimension, particularly as cyberattacks against financial institutions are increasing worldwide. He noted that the financial sector has become one of the most frequently targeted sectors due to the expansion of digital transformation and electronic services.

Al-Gmati called for transparency and the disclosure of investigation results once they are finalized. He also urged a comprehensive review of the digital infrastructure, the strengthening of cybersecurity systems, the enhancement of emergency response plans, and greater investment in specialized national talent.

He emphasized that digital sovereignty has become an integral part of national sovereignty and that the security of financial institutions is no longer measured solely by the size of reserves or the strength of monetary policies, but also by their ability to protect data and systems from growing cyber threats.

According to Al-Gmati, the positive aspect of the incident is that it serves as a wake-up call, encouraging the development of a more efficient and resilient cybersecurity framework that can help safeguard financial stability and strengthen public confidence in the banking sector.

Central Bank of Libya to Sada: Technical Support for Foreign Currency Reservation System Completed; Platform to Resume Operations Tomorrow with Greater Efficiency and Speed

The Central Bank of Libya confirmed exclusively to our source that all technical and technological support work for the foreign currency reservation system has been completed.

The Bank stated that, starting tomorrow, the platform for reserving documentary credits and uploading documents for new reservations will resume operations.

It added that new reservations for personal foreign currency purposes, both in cash and through bank cards, will also resume. The Bank further confirmed that the sale of U.S. dollars will continue through all designated bank branches at a faster pace.